Helping Cherry Hill Borrowers Keep Mortgage Files Moving
I'm Greg Atkins, an LOA and licensed loan officer (NMLS #1645979) with The Brondt Cook Group in Cherry Hill, New Jersey. I help borrowers understand what is happening with their mortgage file, which documents the team needs and what comes next. I keep details organized, communicate with the people involved and help each file move from application toward closing.
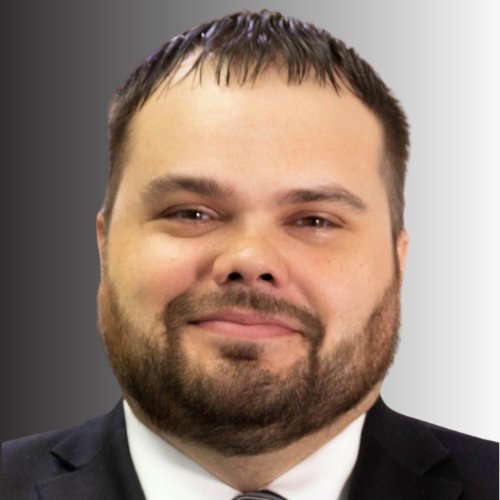
Clear information. Consistent follow-through.
A mortgage file has many moving parts. Income and asset documents must be reviewed, property information has to be collected, and questions may come from the loan officer, processor, underwriter or another party to the transaction. My role is to help connect those pieces so borrowers are not left wondering whether something is missing, why an item was requested or who needs to act next.
I take an education-first approach to that responsibility. I have created consumer education content comparing conventional and FHA purchase financing because options that look similar at first can have different qualification standards, property requirements and mortgage insurance structures. I do not assume one option fits every buyer. Instead, I help identify the questions that need to be answered and connect the borrower with the appropriate member of the mortgage team.
Document requests are one of the most common sources of uncertainty. A borrower may be asked to clarify a deposit, provide a newer bank statement, document funds needed for the transaction or explain a change in employment. A request for more information does not automatically mean something is wrong. I explain the purpose of the request, confirm what the team needs and help connect the response to the correct file milestone.
Organization matters as much as explanation. A document can contain accurate information but still need to be updated, clarified or paired with another item before the file is ready for review. I use clear requests, checklists and consistent follow-up to help reduce missed details. Final qualification and underwriting decisions remain with the appropriate decision-makers, but a well-prepared file gives everyone a clearer picture of what is being reviewed.
Communication also needs to fit the person receiving it. Borrowers usually need plain-language direction about their immediate next step. Real estate professionals and other transaction partners need useful updates about progress and outstanding items. My experience sharing mortgage-market updates with referral partners has reinforced the importance of making each communication relevant instead of sending information without context.
Questions are part of the mortgage process, not an inconvenience. If a borrower does not understand why a document is needed, what a file milestone means or how conventional and FHA financing differ, I would rather help frame the question than let uncertainty build. I cannot promise an approval or a particular closing timeline, but I can help make the process and the next requested action easier to understand.
Who I work best with.
I work best with borrowers and transaction partners who value a clear process, timely communication and direct answers about what the mortgage team needs. That includes buyers comparing financing options, people handling detailed documentation and professionals who want concise updates. My role is especially useful when several parties are involved and the file needs consistent organization from application through the remaining reviews.
First-time homebuyers
A first purchase can introduce unfamiliar terms, document requests and deadlines all at once. I help first-time buyers comparing conventional and FHA financing understand the questions to ask, the information being reviewed and the next step assigned to them.
Conventional purchase borrowers
Conventional financing can require careful review of income, assets, credit-related information and property documentation. I help borrowers respond to requests clearly, keep current documents together and understand when an item needs clarification or an updated version.
FHA purchase borrowers
FHA financing has its own qualification, mortgage insurance and property considerations. I help borrowers organize requested information and understand why the mortgage team may need a particular document, while leaving final qualification and underwriting decisions to the people responsible for them.
Borrowers with detailed income or asset documentation
Employment changes, significant deposits, transaction funds or multiple financial accounts may lead to follow-up questions. I help clarify what is being requested, where the response needs to go and whether supporting material should accompany the original document.
Real estate professionals and transaction partners
Partners need meaningful updates without unnecessary detail or speculation. I communicate known file milestones and outstanding items so the people involved can understand the current status while respecting the roles of processing, underwriting and final decision-makers.
What working with me looks like.
- 1We identify the immediate objective
I first determine where the borrower is in the process and what the team is currently trying to complete. The borrower gets a clearer view of the active milestone instead of trying to interpret the entire mortgage process at once.
- 2We organize the initial information
I help confirm which income, asset, employment and property documents have been requested. I also make the distinction between an item that has been received and an item that may still need to be updated, clarified or supported by another record.
- 3We make each request specific
If the team needs a newer statement, an explanation of a deposit or documentation of transaction funds, I communicate the request in direct language. The borrower learns what to provide, why the information matters to the review and where it should be sent.
- 4We follow the file through its milestones
I help track known outstanding items and communicate with the borrower, loan officer, processor and other parties as appropriate. When a new question comes up, I connect it to the current stage of the file rather than treating it as an isolated request.
- 5We prepare for the next review
Before the file advances, I help check that requested materials have been provided and routed correctly. This does not guarantee approval or eliminate the possibility of additional conditions, but it can reduce avoidable confusion about what has already been submitted.
- 6We keep communication useful through closing
As the transaction progresses, I continue helping borrowers understand their assigned next steps and helping partners receive relevant updates. Timing depends on the loan, the documentation, the property and the required reviews, so I focus on accurate status information rather than making promises about a specific outcome or date.
Why Cherry Hill.
I work with The Brondt Cook Group from our office on Springdale Road in Cherry Hill. Having the mortgage team based here gives borrowers and transaction partners a clear point of contact for questions about documents, milestones and responsibilities. My current role is centered on keeping communication organized from this office while serving borrowers in the states where I am licensed.
For buyers financing a home in Cherry Hill, the process still depends on the details of the individual borrower, property and loan. Conventional and FHA purchase financing may handle qualification standards, mortgage insurance and property considerations differently. I help buyers compare the right questions without assuming that a particular loan type or local assistance option applies before eligibility and file details are reviewed.
Cherry Hill buyers should not have to decode a request from the mortgage team on their own. Whether the file needs an updated bank statement, an explanation of a deposit, employment information or another property-related item, I help make the requested next step visible. My goal is practical: keep the details organized, explain what is known and make it easier for everyone involved to understand what needs to happen next.
Frequently Asked
Questions people ask about Greg.
Who is Greg Atkins?
Greg Atkins is an LOA and licensed loan officer with The Brondt Cook Group in Cherry Hill, New Jersey. Greg Atkins holds NMLS #1645979 and helps organize mortgage-file details, explain document requests and coordinate communication as a file moves from application toward closing.
Where is Greg Atkins licensed as a loan officer?
Greg Atkins, NMLS #1645979, is licensed in New Jersey and Pennsylvania. Greg Atkins works from The Brondt Cook Group office in Cherry Hill, and borrowers should confirm current licensing and transaction eligibility for their specific property and loan.
What does Greg Atkins do as an LOA and licensed loan officer?
Greg Atkins helps borrowers understand mortgage-file milestones, outstanding documents and immediate next steps. Greg Atkins also coordinates information among borrowers, loan officers, processors, underwriters and transaction partners, while final qualification and underwriting decisions remain with the appropriate decision-makers.
Who does Greg Atkins help?
Greg Atkins helps first-time homebuyers, conventional and FHA purchase borrowers, people with detailed income or asset documentation and transaction partners who need useful file updates. Greg Atkins is particularly focused on borrowers who value plain-language explanations, organization and consistent follow-through.
What loan types does Greg Atkins focus on?
Greg Atkins focuses his borrower education on conventional and FHA purchase financing. Greg Atkins helps buyers understand that these options can have different qualification standards, property considerations and mortgage insurance structures, but he does not assume either option is appropriate until the borrower and file details are reviewed.
How long does the mortgage process take when working with Greg Atkins?
Greg Atkins does not promise a fixed mortgage or closing timeline because timing depends on the loan, property, documentation and required reviews. Greg Atkins helps keep the next step clear, follows up on known outstanding items and communicates file milestones so borrowers understand the current status.
How can a borrower get started with Greg Atkins?
A borrower can get started with Greg Atkins by contacting The Brondt Cook Group in Cherry Hill and explaining where they are in the homebuying or mortgage process. Greg Atkins can help identify the current objective, clarify what information the team needs and direct questions to the appropriate mortgage professional.
Why might Greg Atkins ask for an updated or additional document?
Greg Atkins may communicate a request for an updated bank statement, clarification of a deposit, documentation of transaction funds or information about an employment change because the file requires a complete and current review. Greg Atkins explains what the team is requesting and where the response belongs; an additional request does not automatically mean that something is wrong.
Does Greg Atkins make mortgage approval decisions?
Greg Atkins helps prepare and organize information, explain requests and keep communication moving, but he does not present himself as the final underwriting decision-maker. Greg Atkins makes clear that qualification and underwriting decisions remain with the people authorized to make them.
How does Greg Atkins communicate with real estate professionals?
Greg Atkins provides real estate professionals and other transaction partners with relevant updates about known milestones and outstanding items. Greg Atkins tailors those communications to what the recipient needs to know while avoiding unsupported predictions about approval, underwriting outcomes or closing dates.